Line 1: type of group
Boxes for a parent-subsidiary group, brother-sister group, combined group, or life insurance companies only.
1120 Sch. O
Consent Plan and Apportionment Schedule for a Controlled Group
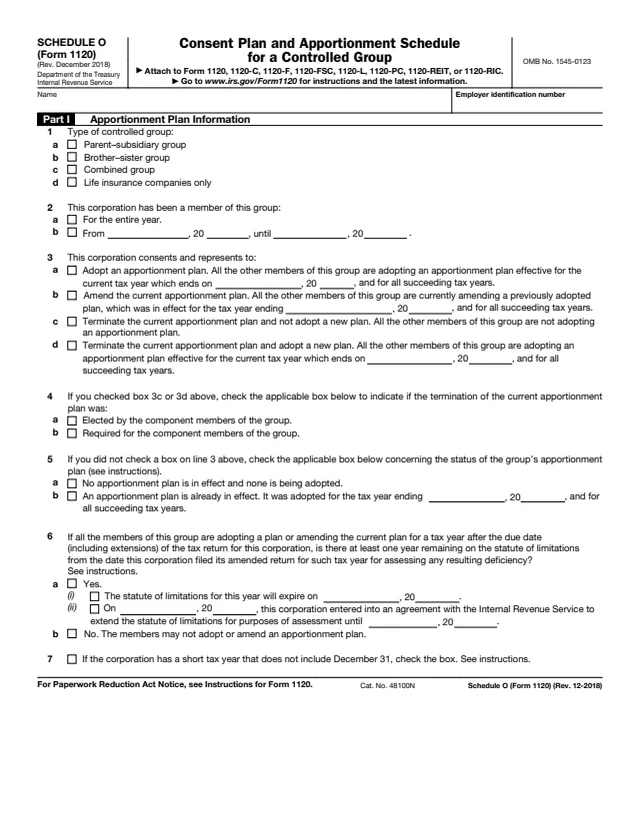
Schedule O (Form 1120), Consent Plan and Apportionment Schedule for a Controlled Group, is filed by corporations that are component members of a controlled group. The instructions say a component member uses it to report the apportionment of certain tax benefits between all component members of the group, and to show whether the group is adopting, amending or terminating an apportionment plan, or already has one in effect.
The form says to attach it to Form 1120, 1120-C, 1120-F, 1120-FSC, 1120-L, 1120-PC, 1120-REIT or 1120-RIC. Part I covers the type of group, the member's status and the plan. Part II lists each member with its share of the accumulated earnings credit, the amount used for the penalty for failure to pay estimated tax, and other tax-benefit items.
The instructions say the December 2018 revision reflects the flat 21% corporate tax rate and the repeal of the corporate alternative minimum tax. You can fill out Schedule O (Form 1120) free in your browser on this page and download the result without an account.
Boxes for a parent-subsidiary group, brother-sister group, combined group, or life insurance companies only.
Whether the corporation was a member of the group for the entire year, or the dates from and until which it was a member.
Boxes to adopt a plan, amend the current plan, terminate it without a new plan, or terminate it and adopt a new plan, with the tax year end.
Whether a termination was elected or required and, if no box on line 3 is checked, whether no plan is in effect or a plan is already in effect.
A statute of limitations question for a plan adopted or amended after the return's due date, and a box for a short tax year that does not include December 31.
Up to 10 members with name and EIN, tax year end (Yr-Mo), accumulated earnings credit, penalty for failure to pay estimated tax, and other items, with a total row.
Enter the name and EIN of the member filing the schedule. In Part II, line 1, enter that member again with its tax year end, then the other members on lines 2 to 10.
Check the type of group. The instructions say a brother-sister group checks 1b whether it applies only the 50% test or both the 80% and 50% tests. Check 2a, or enter the dates on 2b.
Check only one box. Checking a box consents for this corporation and represents that the other members consent too. With no plan being adopted, amended or terminated, the instructions say to skip to line 5.
Check 4a or 4b after box 3c or 3d, check 5a or 5b if line 3 is blank, answer line 6 for a plan adopted or amended late, and check line 7 for a short tax year without December 31.
Column (c) apportions the accumulated earnings credit, column (d) the amount for the estimated tax penalty, and column (e) other items with the Code section. Add "(50)" after a brother-sister member that meets only the 50% test.
A corporation joining or leaving the group that does not qualify as a component member gets "(E)" after its name, its tax year end in column (b), and -0- in the remaining columns.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to attach it to Form 1120, 1120-C, 1120-F, 1120-FSC, 1120-L, 1120-PC, 1120-REIT or 1120-RIC. The instructions also name amended returns and claims for refund.
The instructions say it is filed for each tax year the corporation is a component member, even if no plan is in effect or the amounts apportioned have not changed.
The instructions say the signed apportionment agreement is kept in each member's records and is not attached to the federal income tax return.
The instructions say members may allocate the $250,000 accumulated earnings credit unequally under a plan, and that the amount is $150,000 if a member is a service corporation described in section 535(c)(2)(B).
If no apportionment plan is adopted or in effect, the instructions say members divide the amount of any tax-benefit item equally among themselves.
To amend a plan for a tax year before the 2018 tax year, the instructions point to Schedule O (Form 1120) (Rev. December 2012).

1120
481 fields, 6 pages
1120-C
449 fields, 5 pages
1120-F
527 fields, 9 pages
1120-L
337 fields, 6 pages
1120-PC
565 fields, 9 pages
1120-RIC
325 fields, 4 pages
Corporations that are component members of a controlled group, as the instructions define them.
No tool matches that search.
The instructions say a corporation that is a component member of a controlled group files it with its income tax return, amended return or claim for refund for each tax year it is a component member.
Yes. The instructions say it is filed even if no apportionment plan is in effect or the amounts apportioned have not changed from the previous tax year.
No. The instructions say no member should attach the agreement or a copy of it to its federal income tax return. Each member keeps the original or a copy in its records.
The instructions say the component members divide the amount of any tax-benefit item equally among themselves.
No. The instructions say not to check more than one box on line 3.
No. The instructions say not to include on Schedule O an apportionment of any deduction for property with a section 179 expense election. That apportionment is reported as required under section 179.
The instructions say the common parent of the consolidated group files one Schedule O on behalf of those members, and no subsidiary of that group files its own.