Header
Decedent's name as it appears on Form 706 and the decedent's social security number.
706 Sch. F
Other Miscellaneous Property Not Reportable Under Any Other Schedule
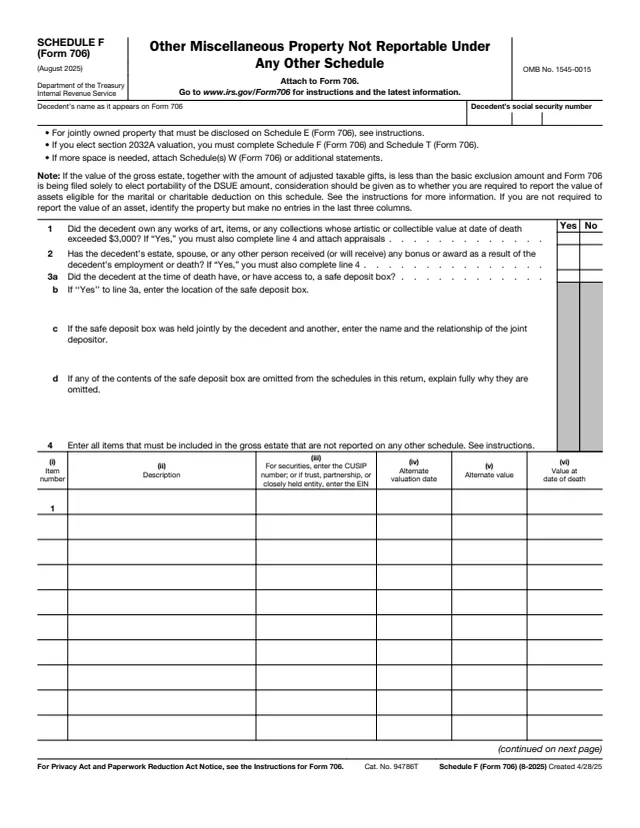
Schedule F (Form 706) is titled Other Miscellaneous Property Not Reportable Under Any Other Schedule. The IRS About page says to use it to include all items that must be included in the gross estate that are not reported on any other schedule. It is attached to Form 706, the United States Estate (and Generation-Skipping Transfer) Tax Return, which the executor of a decedent's estate uses to figure the estate tax.
The Form 706 instructions say Schedule F is completed and filed with the return, and that its questions are answered even if no assets are reported on it. Lines 1 to 3 ask about works of art and collectibles, bonuses or awards tied to the decedent's employment or death, and safe deposit boxes. Line 4 lists the property itself, and the total goes to Form 706, Part V, item 6.
This page has the August 2025 edition. The PDF can be filled out free in the browser on this page and downloaded without an account.
Decedent's name as it appears on Form 706 and the decedent's social security number.
Asks whether the decedent owned any works of art, items or collections whose artistic or collectible value at date of death exceeded $3,000.
Asks whether the estate, spouse or any other person received or will receive a bonus or award as a result of the decedent's employment or death.
Asks whether the decedent had or had access to a safe deposit box, then its location, any joint depositor and why any contents are omitted from the return.
Six columns: item number, description, CUSIP number or EIN, alternate valuation date, alternate value and value at date of death.
The total of column (v) or column (vi), the total from attached Schedule(s) W or statements, and the combined total entered on Form 706, Part V, item 6.
Check Yes or No on each question. The form says a Yes on line 1 or line 2 also means completing line 4, and a Yes on line 1 also means attaching appraisals.
The instructions say that if any item or collection of similar items is valued at more than $3,000, attach an appraisal by an expert under oath and the required statement on the appraiser's qualifications.
Enter gross estate items not reported on another schedule. The instructions list examples such as debts due the decedent, interests in business, digital assets, royalties, household goods, livestock, farm machinery and automobiles.
For a partnership or unincorporated business, the instructions say to attach statements of assets and liabilities and of net earnings for the valuation date and the 5 years before it, and to include the entity's EIN.
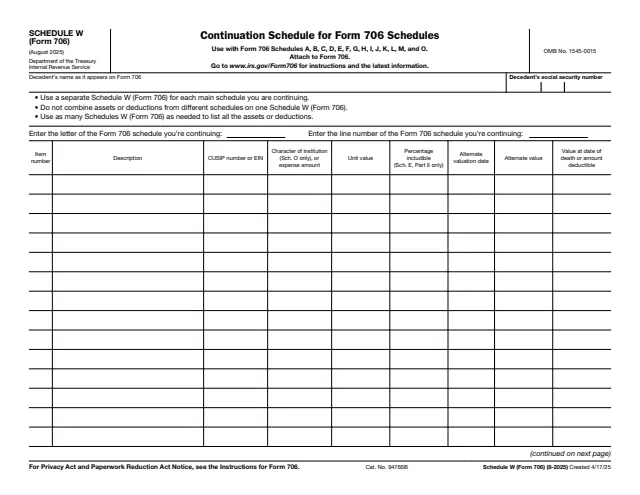
Enter the value at date of death in column (vi). Columns (iv) and (v) hold the alternate valuation date and alternate value. If more space is needed, attach Schedule W (Form 706) or additional statements.
Add column (v) or column (vi) on line 5, enter the Schedule W or statement total on line 6, and enter the line 7 total on Form 706, Part V, item 6.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
Schedule F is attached to Form 706. The instructions give the Form 706 address as Department of the Treasury, Internal Revenue Service, Kansas City, MO 64999.
The instructions say Form 706 is filed within 9 months after the date of the decedent's death, and Form 4768 is used to apply for an automatic 6-month extension of time to file.
Appraisals for collectibles over $3,000, Form 712 for each policy of insurance on the life of another, and a copy of the trust instrument for shares in trust funds.
If Form 706, Part IV, line 11b is answered Yes for a business interest, the instructions say to attach a statement with the line and item number from Schedule F and the total effective discount taken.
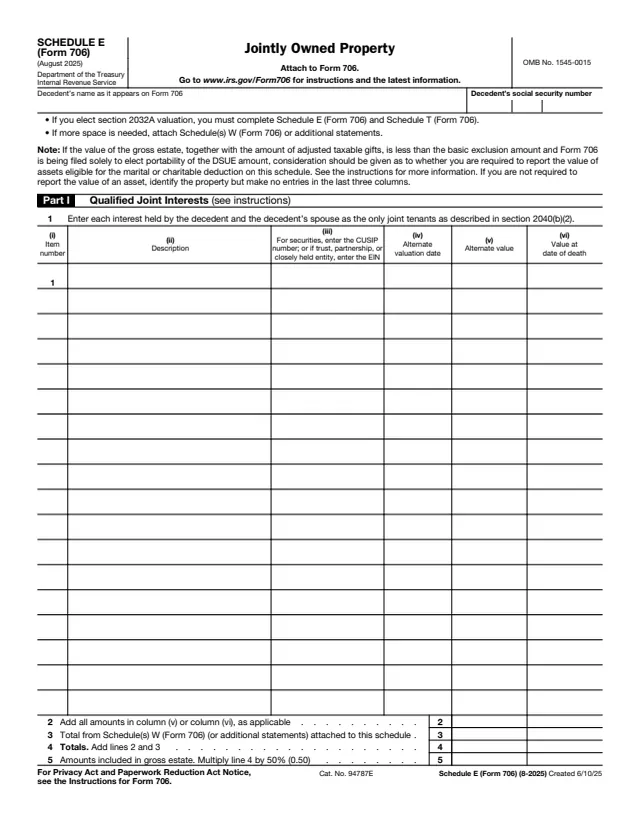
The form points jointly owned property to Schedule E (Form 706). The instructions say jointly owned partnership interests go on Schedule E and other partnership interests on Schedule F.
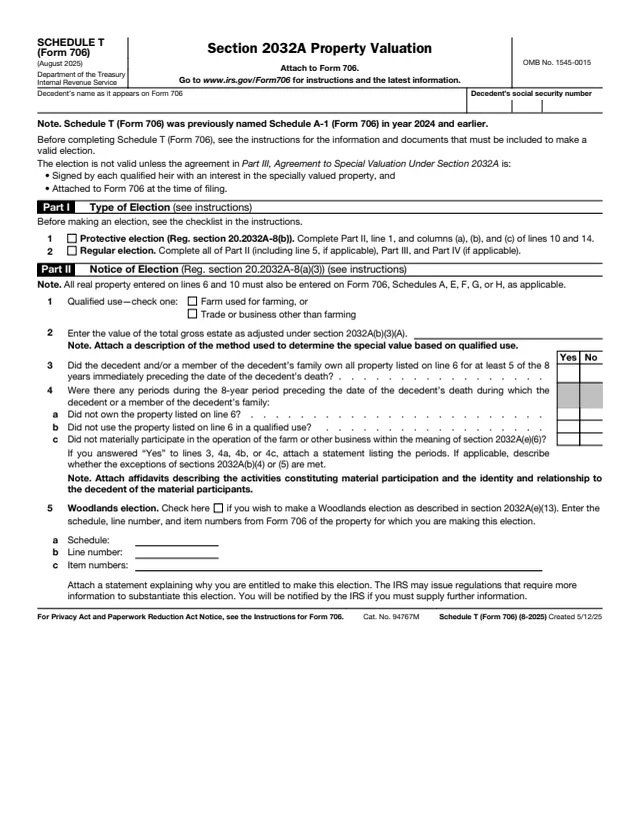
The form says that if section 2032A valuation is elected, Schedule F (Form 706) and Schedule T (Form 706) are both completed.

706
316 fields, 5 pages
706 Sch. E
265 fields, 2 pages
706 Sch. W
303 fields, 2 pages
706 Sch. T
858 fields, 8 pages
712
91 fields, 3 pages
706 Sch. A
223 fields, 2 pages
The executor filing Form 706 for a decedent's estate completes Schedule F as part of the estate tax return.
No tool matches that search.
The Form 706 instructions list it among the schedules to attach and say to answer its questions even if no assets are reported on it.
The instructions list digital assets for Schedule F. They define them as digital representations of value recorded on a cryptographically secured distributed ledger or similar technology, such as NFTs, cryptocurrencies and stablecoins.
The form says to enter the line 7 total on Form 706, Part V, item 6.
The instructions say to attach an appraisal by an expert under oath if any item or collection of similar items is valued at more than $3,000.
On Schedule F, the instructions say, unless the partnership interest is jointly owned. Jointly owned partnership interests are reported on Schedule E (Form 706).
The form says to attach Schedule(s) W (Form 706) or additional statements, and enter their total on line 6.