Header and note
The PSC's name and employer identification number, and a note about newly organized PSCs and corporations that become PSCs.
1120
Section 280H Limitations for a Personal Service Corporation (PSC)
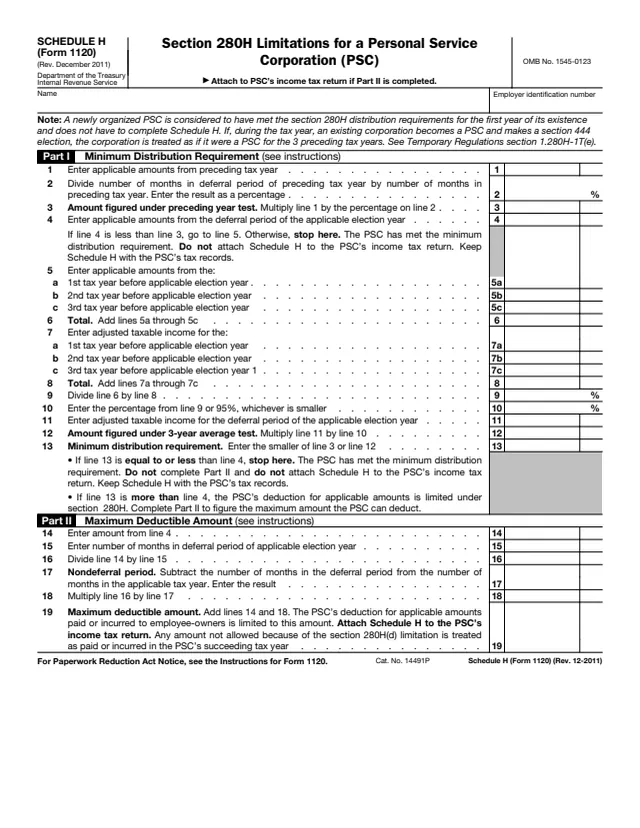
Schedule H (Form 1120), Section 280H Limitations for a Personal Service Corporation (PSC), is used by a PSC that elects to have a tax year other than a calendar year. The About page says the PSC uses it to determine if it meets the minimum distribution requirement for the tax year, or to figure the limits on deductions if the requirement is not met.
The instructions explain that a PSC making a section 444 election is subject to the minimum distribution requirement of section 280H for the election year and each tax year the election remains in effect. If it does not meet the requirement, its deduction for amounts paid or incurred to employee-owners is limited.
Part I tests the requirement and Part II figures the maximum deductible amount. The instructions are printed on page 2 of the PDF. You can fill out the PDF free in your browser on this page and download it without an account.
The PSC's name and employer identification number, and a note about newly organized PSCs and corporations that become PSCs.
The preceding year test: applicable amounts from the preceding tax year, the deferral period percentage, and applicable amounts from the deferral period of the election year.
The 3-year average test: applicable amounts and adjusted taxable income for each of the 3 tax years before the election year.
The minimum distribution requirement, the smaller of line 3 or line 12, compared with line 4.
Deferral and nondeferral period figures used to spread the deferral period amount over the rest of the tax year.
The maximum deductible amount for applicable amounts paid or incurred to employee-owners.
Enter the applicable amount paid or incurred in the preceding tax year to any employee-owner of the PSC that was otherwise deductible on the PSC's preceding income tax return.
Line 2 divides the months in the preceding year's deferral period by the months in that year. Line 3 multiplies line 1 by it. If line 4 is not less than line 3, the form says to stop.
Enter applicable amounts and adjusted taxable income for the 3 tax years before the election year. Line 10 is the smaller of line 9 or 95%. Line 12 multiplies line 11 by line 10.
Enter the smaller of line 3 or line 12. If line 13 is equal to or less than line 4, the form says the PSC has met the requirement and Part II is not completed.
Copy line 4 to line 14 and divide it by the months in the deferral period. Multiply the result by the months in the nondeferral period on line 17.
Add lines 14 and 18. The form says the deduction for applicable amounts paid or incurred to employee-owners is limited to this amount.
You get the real form, filled in a browser tab, with nothing standing between you and the finished PDF.
The form says to attach Schedule H to the PSC's income tax return if Part II is completed.
When the PSC meets the minimum distribution requirement, the form says not to attach Schedule H and to keep it with the PSC's tax records.
Line 19 says any amount not allowed because of the section 280H(d) limitation is treated as paid or incurred in the PSC's succeeding tax year.
The instructions define it as the months between the last day of the elected tax year and the last day of the required tax year. A September 30 year end gives 3 months.
The instructions say this is a person who is an employee of the PSC or performs services for it, including an independent contractor, and owns any outstanding stock of the PSC.
The instructions say dividends paid by the corporation and gain on the sale or exchange of property between the owner-employee and the corporation are not applicable amounts.

1120
481 fields, 6 pages
1120
114 fields, 2 pages
1120 Sch. G
92 fields, 2 pages
1120 Sch. O
112 fields, 2 pages
1120 Sch. B
24 fields, 2 pages
1120-X
70 fields, 2 pages
The schedule is completed by a corporation, not by an individual. It goes with the PSC's income tax return or stays in its records.
No tool matches that search.
No. The instructions say a PSC with a section 444 election completes it, but attaches it to Form 1120 only when it does not meet the minimum distribution requirement.
The instructions say the PSC meets it if applicable amounts for all employee-owners during the deferral period equal or exceed the smaller of the preceding year test or the 3-year average test.
The instructions say it is any amount otherwise deductible by a PSC in a tax year that is includible, directly or indirectly, in the gross income of an employee-owner during that year.
Line 19 says any amount not allowed because of the section 280H(d) limitation is treated as paid or incurred in the PSC's succeeding tax year.
For the deferral period of an applicable election year, the instructions say reasonable estimates are acceptable.